Materials

A Complete Map of "Small and Beautiful" Hidden Champions in Semi Materials

The semiconductor industry is often associated with famous chip designers, leading foundries, and advanced equipment manufacturers. Companies developing processors, memory chips, and lithography systems frequently receive global attention because their products directly influence technology trends. However, behind every advanced semiconductor device exists a complex ecosystem of specialized material suppliers that quietly enable the entire industry.
Certification Barriers and Breakthrough Cases for Chinese Material Firms Entering Global Supply Chains

The global semiconductor industry is undergoing a major transformation as supply chains become more diversified, regionalized, and strategically important. Semiconductor materials, once considered a relatively stable part of chip manufacturing, have become one of the most critical competitive areas in the industry. For Chinese semiconductor material companies, entering global supply chains represents both a significant opportunity and a complex challenge. While China has developed strong capabilities in many material segments, gaining acceptance from international semiconductor manufacturers requires overcoming strict certification barriers, technological requirements, and long-established supplier relationships.

CMP Pad and Slurry Market Structure: The Moats of DuPont and Cabot

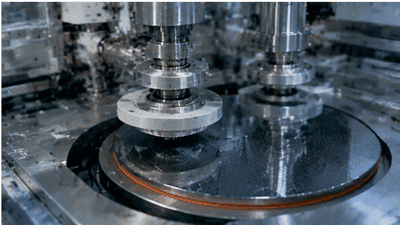
Chemical mechanical planarization (CMP) is one of the most critical yet often understated processes in semiconductor manufacturing. It quietly ensures that wafers maintain the flat, precisely controlled surfaces needed for successive lithography, etch, and deposition steps. At the center of CMP are two indispensable consumables: pads and slurries. Over the past decades, a small group of global players—most prominently DuPont and Cabot—have built strong positions around these products, developing what can fairly be described as “moats” in the CMP pad and slurry market structure.

The Material System Transition of Sputtering Targets (Al/Cu/Ti/Co) in Advanced Interconnects

Advanced interconnects have quietly become one of the most challenging frontiers in semiconductor manufacturing. As device performance, power efficiency, and reliability demands tighten at each new logic and memory node, the wiring that connects transistors and functional blocks has evolved just as dramatically as the transistors themselves. Central to this evolution is the material system used in thin-film deposition, especially sputtering targets based on aluminum (Al), copper (Cu), titanium (Ti), and cobalt (Co). The transition in these target materials reflects a broader shift in how the industry manages resistance, electromigration, barrier integrity, and manufacturability in increasingly complex interconnect stacks.

Impact of Germanium/Gallium Export Controls on Semi Material Supply Chains

The semiconductor industry has entered a new era in which material security has become as important as technological innovation. For decades, the global chip industry focused primarily on advancing transistor performance, increasing manufacturing efficiency, and expanding semiconductor capacity. However, recent supply chain disruptions and geopolitical tensions have highlighted a critical reality: access to specialized materials can determine the stability and competitiveness of the entire semiconductor ecosystem.

New Application Scenarios of Silicon-Based Materials in 3rd-Gen Semi Substrates

Third-generation semiconductor substrates such as silicon carbide (SiC) and gallium nitride (GaN) are reshaping power electronics, RF devices, and high‑efficiency energy systems. They are often described as a break from traditional silicon, yet silicon‑based materials have not disappeared from the picture. Instead, they have found new, strategically important roles around these wide‑bandgap substrates: as templates, integration platforms, thermal and mechanical partners, and key elements in hybrid packaging. The interplay between silicon and third‑generation semiconductors is becoming a central theme in how next‑generation devices are designed and manufactured.

Empirical Analysis of Price Transmission from Material to Foundry End

The semiconductor industry is built upon one of the most complex and interconnected supply chains in the global manufacturing economy. From raw materials and specialty chemicals to semiconductor equipment, wafer fabrication, packaging, and final electronic products, each stage influences the economics of the entire value chain. Among these relationships, the transmission of price changes from semiconductor materials to foundry manufacturing costs has become an increasingly important topic as the industry experiences supply shortages, capacity expansions, and technology transitions.

2026 Photoresist Localization Target of 20%: Which Companies Benefit Most?

The semiconductor industry is entering a period of accelerated transformation as countries and companies increasingly focus on supply chain security, technological independence, and domestic manufacturing capabilities. Among the many semiconductor materials requiring localization, photoresists have become one of the most strategically important categories due to their direct impact on lithography performance, wafer yield, and advanced semiconductor production.    

  • 1
  • 2
  • 3